Sudden Storm Damage
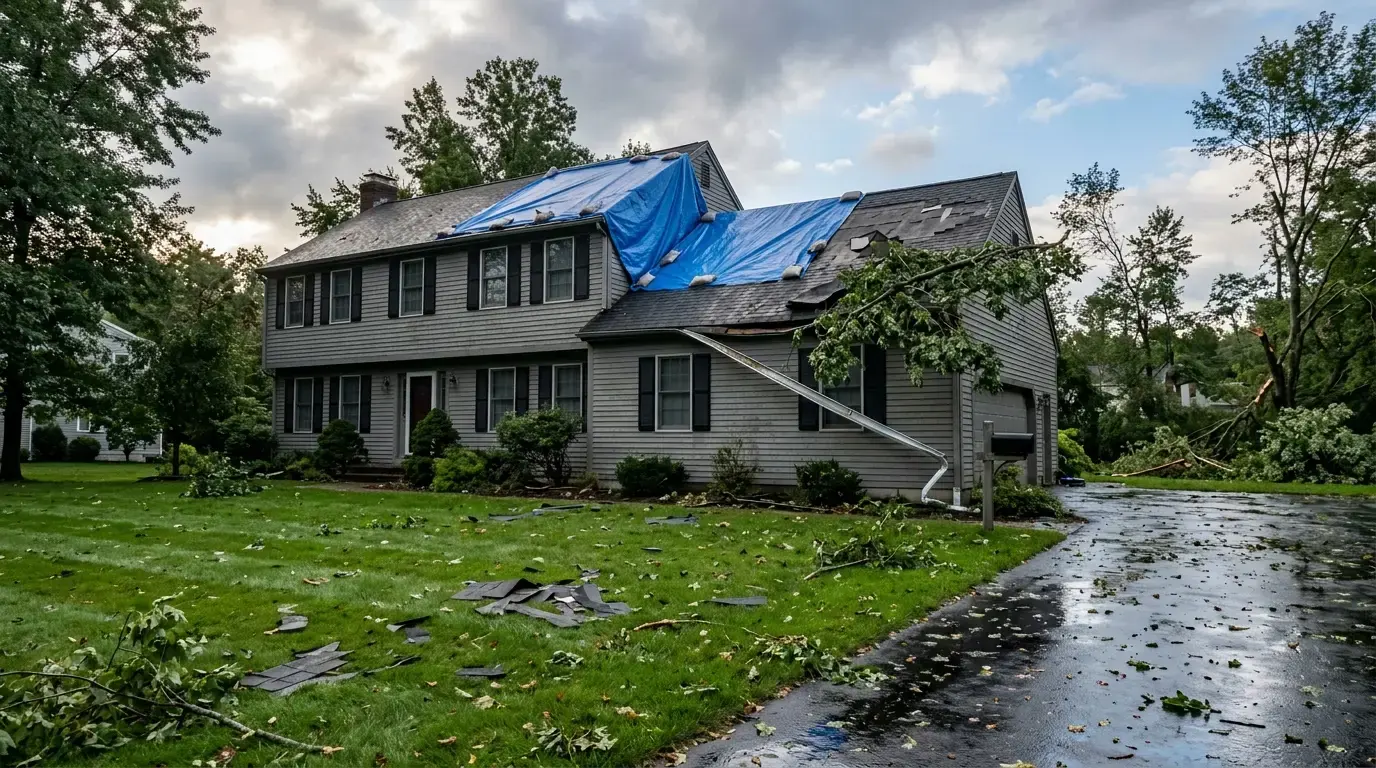
Sudden damage from a specific event. Wind tearing shingles loose, hail bruising the surface, a limb coming through the deck, or a storm driving water past intact flashing. The common thread is a dated event that caused it.
Free roof inspections, dated photo documentation and a written damage report for your Connecticut insurance claim. You file with your insurer. We document the damage and do the repair work.
Roof insurance claims go badly for predictable reasons: the damage was never properly documented, the homeowner did not know what their own policy covered, or a contractor promised something that was never theirs to promise. This page covers all three, plainly.
Sudden damage from a specific event. Wind tearing shingles loose, hail bruising the surface, a limb coming through the deck, or a storm driving water past intact flashing. The common thread is a dated event that caused it.
Gradual deterioration. A roof that reached the end of its life, leaked slowly for years, or failed because maintenance never happened. Insurers treat wear as an owner expense, not a covered loss, and adjusters are trained to see.
Old roofs damaged by a real storm. The event is covered, but age changes what the policy pays, and some carriers handle older roofs under different terms. This is where documentation matters most, and where claims get argued.
Damage smaller than your deductible. A claim that pays nothing but stays on your record helps nobody. Sometimes the honest answer is to pay for a repair directly and keep the claim history clean for something larger later.
A storm hits. Note the date, because every step after this gets tied back to that specific day.
We inspect the roof and exterior, then document what failed with clear dated photographs and a written report.
Check your deductible and whether the roof is covered at replacement cost or actual cash value before calling.
You contact your insurance company and open the claim yourself, using our documentation to describe the damage accurately.
The insurer sends an adjuster to inspect. Your photos and report give that visit a clear starting point.
Once you and the insurer settle the claim, our crew performs the work from the written scope agreed.
Almost nobody in the industry explains this clearly. So we will — three separate roles, three separate accountabilities.
You own the policy and the claim. You decide whether to file, you talk with your insurer, and you approve the repair scope. Nobody can do that for you without a public adjuster license.
We inspect the roof, document damage with dated photos, write a clear repair scope and perform the work once your claim settles. Everything we produce belongs to you, claim or no claim at all.
The adjuster works for your insurance company, inspects the damage and determines what the policy covers. They are not really your opponent in this process, but they are also not working on your behalf.
Under Connecticut law (CGS 38a-723), preparing, submitting or negotiating a first-party property claim on someone’s behalf for compensation is public adjuster work and requires a state license. We inspect, document and repair. You file your own claim.
The amount you pay before coverage starts. It is a contractual obligation, not a discount, and any contractor offering to cover it is proposing fraud.
Pays what it costs to replace the roof at today’s prices. Better coverage, a higher premium, and the difference shows up when you actually file.
Pays replacement cost minus depreciation for age. On an older roof that can mean a payout well below what the work actually costs to complete.
Some policies carry a separate deductible for wind or hail damage, often calculated as a percentage of the dwelling coverage rather than a flat amount.
Your policy decides all of this. Read the roof section before you call anyone, including us.
Six red flags that appear repeatedly across storm-chaser complaints in Connecticut. If you hear any of these, walk away.
Offers to waive, cover or absorb your insurance deductible entirely.
Promises the roof will cost you nothing out of pocket.
Asks you to sign a contract before the claim settles.
Says they will handle, file or negotiate your claim entirely.
Shows up uninvited days after a storm with urgent pressure.
Cannot produce a Connecticut registration or a local business address.
Get the damage documented first. Free inspection, dated photos and a written report you keep, whether you file a claim or not.
Damage documentation delivered same week · no obligation to file.